Every write-off that saves you money in April costs you buying power at the closing table. A bank statement loan qualifies you on what actually hits the account. Answer three questions and I will tell you where you stand.
No credit pull to get an answer · No tax returns · One originator who answers his own phone
Every deduction that saves you money in April costs you buying power at the closing table. A conventional underwriter reads the net income at the bottom of your return — after mileage, home office, equipment, phone, meals. You might gross $400,000 and show $60,000. That is correct tax strategy and terrible mortgage strategy, and nobody warns you until you are already denied.
Net profit after every legitimate write-off, averaged over two years. If the trend is down, they use the lower year. This is why good years get punished.
Twelve or twenty-four months of deposits, with an expense factor applied. Your write-offs stop working against you because the return never enters the calculation.
Pricing runs above conventional, and lenders want more of your own money in the deal. If your return does support the loan, take conventional — it is cheaper and I will tell you so.
Contractors, agents, truckers, salon owners, consultants, restaurant operators. Anyone whose deposits tell a truer story than their return does.
Move the sliders to your real numbers. The expense factor is what the lender assumes your business costs are — it varies by lender and by industry, and it is one of the biggest levers in the whole file.
Illustrative arithmetic only. Not a quote, a loan offer, a commitment to lend or a pre-approval. Expense factors, income calculation methods, allowable statement periods and DTI ceilings vary materially by lender and by business type; many lenders require a CPA letter or business license to support a lower expense factor.
These cost you nothing and they are the difference between a clean approval and six weeks of document requests. Most originators will not tell you until it is already a problem.
Every transfer between your own accounts reads as a deposit to an underwriter and has to be sourced and excluded. Two weeks of your life, gone. Pick one deposit account and leave it alone until you close.
Undocumented cash generally cannot be counted, and large unexplained deposits raise questions about the whole file. If your business is cash, we build the documentation deliberately — that is a conversation, not a form.
Not a truck, not a business line, not a store card. Every new account moves your DTI and your score at exactly the wrong moment. If you need equipment, tell me first and we will time it.
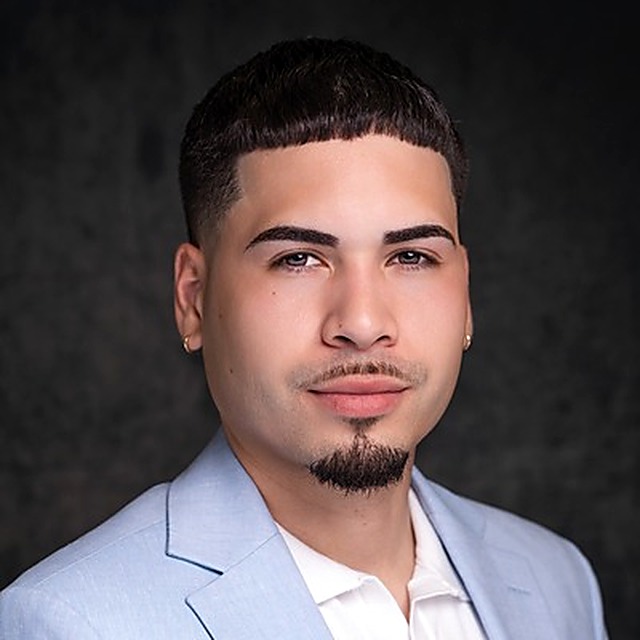
Michael Theut, home builder turned mortgage loan originator, serving all of Florida. Brokered through NEXA with 290+ lenders behind him — which on a bank statement file matters more than anywhere else, because the expense factor is a lender-by-lender negotiation.
Seventeen closings since February 13, 2025. Not a big number, and I do not dress it up. What it buys you: I know every one of those borrowers' names, and when you call, you get me.
Most programs use twenty-four months. Some lenders write on twelve, usually with a pricing or down payment tradeoff. Personal-account statements are allowed by some lenders when deposits land there instead of a business account, generally with a different expense factor.
It is the percentage of your deposits the lender assumes went to business expenses. A 50% factor on $33,000 of monthly deposits gives you $16,500 of qualifying income; a 20% factor gives you $26,400. Same deposits, wildly different approvals.
Factors vary by lender and by industry, and many lenders will accept a lower factor with a CPA letter or a P&L. This is the single most valuable thing a broker does on these files — and it is why shopping one lender is a mistake.
Yes, meaningfully. That is the honest answer. The right way to decide is to price both, the same day, same lock period, and look at the total cost over the years you actually plan to hold the loan. If conventional works, take conventional. I will run both and tell you which one wins.
More than a conventional loan in most cases. The exact amount depends on your credit, the property type and how your income calculates, and I’ll give it to you in writing. Reserve requirements also apply and scale with loan size.
Yes. Bank statement programs replace the income documentation, not the credit standard. Most start around a 620–660 minimum with materially better pricing above 700. And in my experience the actual reason people get denied is rarely the score — it is debt-to-income, which you can often fix in weeks.
You can, though for a rental a DSCR loan is usually the better tool because it ignores your personal income entirely. Bank statement is the right answer for the house you are going to live in.
Then I say so. I told a client no last month on a loan that would have approved, because it approved at his absolute ceiling with no reserves. That cost me a commission. If your return supports conventional, or if the right move is to wait eight months, you will hear it from me first.
Or bring me twelve months of statements before you apply anywhere and we will build the file right the first time. Either way you get a straight answer, and if conventional is cheaper for you, that is what I will tell you.