A DSCR loan qualifies you on what the property earns, not what your return shows. No W-2s, no personal debt-to-income, no two years of self-employment history. Answer three questions and I will tell you where you stand.
No credit pull to get an answer · No tax returns · One originator who answers his own phone
DSCR stands for Debt Service Coverage Ratio. Market rent divided by the full monthly payment — principal, interest, taxes, insurance and HOA. If the property carries itself, you are in the conversation. No W-2s, no tax returns, no two-year self-employment history, no personal debt-to-income calculation.
Good accounting shows little net income. That is correct tax strategy and terrible mortgage strategy. DSCR does not look at it.
Already at the conventional limit on financed properties? DSCR does not count your personal debt against you, so the portfolio can keep growing.
DSCR pricing runs above conventional, and lenders want more of your own money in the deal. That is the trade. If you qualify conventionally with room, take the cheaper money — I will tell you so.
QM lending in Florida; DSCR and non-QM investor loans in select states nationwide. One originator, 290+ lenders behind him, and he answers his own phone.
Move the sliders. No email, no phone number, nobody calling you. Insurance is a separate field on purpose — in Florida it is the line that decides most of these deals.
Use the figure from your lender quote or Loan Estimate.
Illustrative arithmetic only. Not a quote, a loan offer, a commitment to lend, a rate lock or a pre-approval. Actual DSCR calculation methods vary by investor; some use gross rent, others apply adjustments. The payment is an input you supply from your own quote. Insurance and tax figures are yours to supply — get a bindable insurance quote before you write an offer.
Insurance sits inside the payment, so every dollar of premium comes straight off your ratio. I have watched files pencil at 1.10 and die at 0.95 when the bindable quote came back. Move the insurance slider above and watch what happens.
Not after the inspection. A bindable quote inside your due-diligence window is the single most valuable thing you can do on a Florida rental.
Many carriers decline shingle roofs past 15 years regardless of condition. It does not matter that it does not leak. I built houses before I financed them — I will ballpark the re-roof before you are under contract.
Federal Pacific and Zinsco panels, cloth or aluminum branch wiring, grey polybutylene pipe. Any of these sends you to a specialty carrier at a specialty price — and that price is what your ratio gets calculated on.
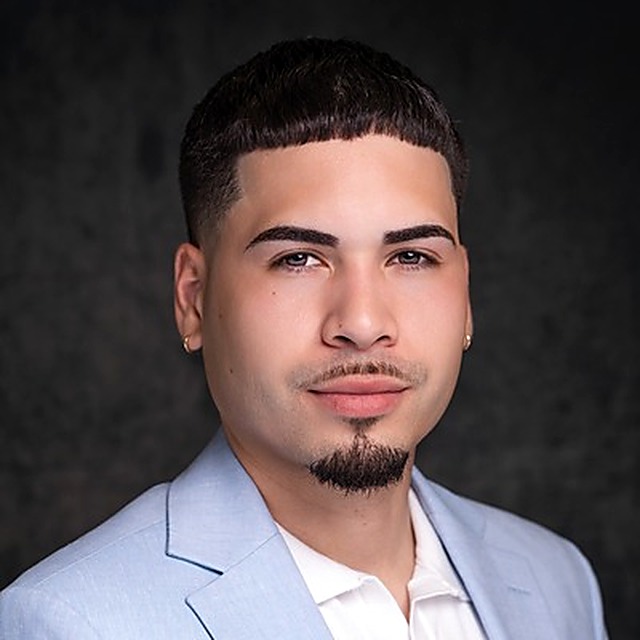
Michael Theut, home builder turned mortgage loan originator. Serving all of Florida. QM lending licensed in Florida; DSCR and non-QM investor loans written nationwide through NEXA's 290+ lender network.
Seventeen closings since February 13, 2025. That is not a big number and I do not dress it up. Here is what it buys you: I can tell you every one of those borrowers' names. When you call, you get me — no assistant, no queue, no script.
No. DSCR loans qualify on the property's rental income rather than your personal income, so tax returns, W-2s and employment history are generally not required. The lender still verifies your credit, your assets and reserves, and the property itself.
If you were denied on an investment purchase because of your tax returns, that was a conventional answer to a DSCR question.
Most programs price best at 1.20 or above. Many lenders will go to 1.00. Sub-1.00 and no-ratio programs exist at a higher rate and a larger down payment. The calculator above uses gross rent divided by full PITIA, which is the most common method — some investors calculate it slightly differently.
Generally yes, and many lenders prefer it. A personal guaranty is typically still required, so an LLC changes the vesting and often the credit reporting — it does not make the debt disappear. Underwriters on your next file will ask about it, and you should disclose it.
Most DSCR loans carry one, commonly running zero to five years. You can usually buy it out, which raises the rate. If you plan to sell or refinance inside eighteen months, price the buyout before you lock, not after. This is the single most common regret I see on these files.
Typically three to twelve months of PITIA, scaling with loan size and the number of properties you already finance. And a word beyond the guideline: a property at 1.02 with two months of reserves is one vacancy from a real problem. The loan may approve. That does not make it a good idea, and I will say so.
Commonly three to four weeks, sometimes faster, because there is no income documentation to chase. The two things that actually delay these files are insurance binders and condo questionnaires. Start both on day one and this is a fast loan.
Then I tell you. I told a client no last month on a file that would have approved, because it approved at his absolute ceiling with no reserves on a house needing a roof. That cost me a commission and he is closing with me in the spring. Approved and affordable are two different words.
I will run the ratio with a real Florida insurance estimate in it instead of a placeholder, and tell you what it comes out to before you write an offer. If it does not work, I would rather say so on day one.